
Seeking Agents® is a platform that connects real estate agents with motivated Buyers and Sellers who are actively seeking representation. Agents can gain access to high-quality leads and grow their business without spending a fortune on marketing.
Help Center
Frequently Asked Questions
Search or browse topics below.
Common Searches
Buyers and sellers: Compare participating agents' proposed services, experience, and negotiable fees at no cost to use Seeking Agents®. Choose whether to connect, with no obligation to select an agent.
Agents: Start with the free Starter plan or choose a paid plan for additional benefits. Standard Basic for new enrollment is $25 per month, with five monthly Offer Tokens and five additional selectable ZIPs beyond your included permanent coverage. Monthly tokens expire 45 days after issuance. Existing subscriptions may have different benefits.
Seeking Agents® helps agents present their services to people seeking representation. Lead volume, selection, transactions, and savings are not guaranteed.
Related links:
Buyers and sellers: Seeking Agents® is free to use to request and compare agent offers, with no obligation to choose an agent. Fees for an agent's services are separate and negotiated directly with that agent.
Agents: Start with the free Starter plan, with no credit card required. Starter includes two one-time, non-expiring Offer Tokens and an included permanent service area. Standard Basic for new enrollment is $25 per month and includes five monthly Offer Tokens and five additional selectable ZIP codes. Monthly tokens expire 45 days after issuance. Existing subscriptions may have different preserved benefits; review your account and the current plan details before enrolling.
Related links:
No, Seeking Agents® is a cutting-edge platform designed to empower home buyers and sellers by connecting them with licensed real estate agents in a competitive marketplace. We are not a real estate brokerage and do not participate in or influence purchase or listing agreements. Instead, we focus on facilitating connections to ensure you find the right agent for your unique needs. By emphasizing transparency and choice, we help you make confident decisions for your real estate journey.
- Agents Compete for Your Business: You receive multiple offers from agents, allowing you to compare real estate agents, services, and pricing.
- Potential Commission Savings: Because agents compete, you may secure a lower commission rate, saving you money.
- No Cost, No Obligation: Seeking Agents® is completely free for Buyers and Sellers, and you are not obligated to choose an agent.
- You Stay in Control: You decide when and if you want to share your contact information with an agent.
- Personalized Matches: Agents make offers based on your criteria, ensuring you receive proposals tailored to your needs.
By using Seeking Agents®, agents compete to represent you in buying or selling your home. This competition allows you to negotiate the commission percentage, helping you save money on your real estate transaction. You can also use the real estate commission calculator to estimate potential savings.
Yes. Real estate commissions are negotiable, and the right structure can depend on your price point, market, services, and whether agents are competing for your business. Start with our commission comparison guide, then use the real estate commission calculator to estimate possible savings.
Seeking Agents® lets buyers and sellers compare participating agents' proposed services and negotiable fees before choosing whom to connect with. The platform is not a real estate brokerage, and buyers and sellers are not obligated to choose an agent.
Agents can start free with Starter or enroll in an available paid plan. Multiple agents may cover the same ZIP and compete for a request, so opportunities are not exclusive. Compare the current plan benefits and your account's terms before enrolling.
Related links:
- Enter Your Buying or Selling Criteria: Provide basic details about your real estate needs.
- Agents Review Your Request: Licensed real estate agents in your area will see your request and submit offers.
- Compare Offers: Review offers from multiple agents, including their commission rates, services, and experience. Our agent comparison guide can help you know what to weigh.
- Decide When to Connect: If you find an agent you like, you can choose to connect and start working together. Until then, your contact information remains private.
We are slowly rolling out across the nation.
To find out if we have agents, sellers or buyers in your area.
Contact us at info@seekingagents.com
Contact us at info@seekingagents.com
The NAR settlement changed certain practices for participating real estate professionals, including written buyer agreements and how offers of buyer-agent compensation are communicated. Real estate commissions remain negotiable.
- When a participating agent works with a buyer, a written buyer agreement is generally required before touring a home together. The agreement describes the services and compensation; state law and the circumstances of the showing also matter.
- A seller or listing broker may offer compensation to the buyer's broker, but offers of compensation cannot be displayed on participating MLSs.
- Your payment obligations depend on your agreement. Discuss any shortfall in seller-paid compensation before committing to a purchase.
- The buyer's broker cannot receive more compensation than the amount agreed with the buyer. A larger seller offer does not automatically entitle the buyer to cash or a credit; any proposed credit must comply with the transaction and financing rules.
Seeking Agents® helps you compare agents and their proposed services and fees. Review the agreement with your agent and, where appropriate, an attorney before signing.
Related links:
No, absolutely not! You are in complete control of the process. Agents can only access your information once you decide to connect with them. Until then, your contact details remain private.
A probate home sale is a sale handled as part of administering a deceased person's estate under the applicable probate process. Not every inherited home requires probate; ownership structure, estate planning, and state law matter.
The authorized personal representative works with the estate's attorney and other professionals to establish authority, address title and estate obligations, and complete any required notices, approvals, or court procedures. The sale proceeds are handled under the estate's legal obligations before distribution.
Timing varies substantially. Confirm the representative's authority and any court requirements before listing or accepting an offer. Seeking Agents® can help you compare participating agents and their relevant experience; an agent does not replace estate counsel.
Decisions about a family home during divorce depend on ownership, state law, agreements, financing, and court orders. Possible arrangements include a sale, a buyout, or temporary continued co-ownership.
Removing a name from the deed does not release that person from the mortgage. Refinancing, an approved assumption or release, or another lender-approved arrangement may be needed to change loan responsibility; none is automatic.
Before acting, have your attorney review authority to sell or transfer, valuation, division of proceeds, and any restrictions. Discuss tax consequences with a tax professional. An agent can provide market information and sale services but does not decide legal rights or replace independent legal advice.
First-time homebuyer eligibility depends on the specific loan or assistance program. Many programs use a three-year lookback for ownership of a principal residence, but exceptions, spouse rules, and the treatment of previous ownership vary.
Other requirements may include income and purchase-price limits, intended occupancy, credit eligibility, and homebuyer education. FHA financing is not limited to first-time buyers. Ask the program administrator or lender to review your household's ownership history before assuming that you qualify.
Related links:
We never see or store your credit card information. All payment processing is securely handled by Stripe, ensuring your details remain completely off our platform.
We’re here to help!
You can reach out to Seeking Agents® directly via phone or email for any additional questions.
Our representatives are available during regular business hours (7 AM to 7 PM PT):
📞 Phone: 833-733-5248
For Information: info@seekingagents.com
For Support: support@seekingagents.com
We look forward to assisting you!
You can reach out to Seeking Agents® directly via phone or email for any additional questions.
Our representatives are available during regular business hours (7 AM to 7 PM PT):
📞 Phone: 833-733-5248
For Information: info@seekingagents.com
For Support: support@seekingagents.com
We look forward to assisting you!
We do not sell your personal information or provide it to unrelated third parties for their own marketing. We share information with trusted service providers that help operate and secure Seeking Agents®, and in other circumstances described in our Privacy Policy, such as legal requirements.
Your identifying information is disclosed to a participating real estate professional only after you choose to connect through the platform and that professional accepts the connection. Creating an account or submitting an inquiry does not by itself distribute your contact details to multiple agents.
Not necessarily. Whether an inherited home can be sold without every heir's agreement depends on title, the will or trust, the representative's authority, state law, and any court orders or required notices.
Heirs may have rights to notice or objection, and disagreements can affect the process. Do not assume that an executor will prevail in a dispute or that a sale can proceed simply because one party considers it reasonable. Ask the estate's attorney to establish who may authorize and sign the sale.
Seeking Agents® can help you compare agents with relevant experience once the legal authority and sale process are clear.
Related links:
Whether one spouse can sell a home without the other's agreement depends on title, applicable marital or homestead rights, state law, and any court orders. A jointly owned home commonly requires participation by both owners or valid legal authority to proceed.
During divorce, restrictions may apply even if only one spouse appears on title. If the parties disagree, ask a divorce attorney what agreements or court action are needed before listing, signing, or transferring the property.
A real estate agent can help market an authorized sale and coordinate practical steps with counsel. The agent cannot replace a required signature, resolve ownership rights, or guarantee that a court will order a sale.
Related links:
Seeking Agents® delivers leads from individuals who are actively searching for representation in their real estate transactions. These are people who have already decided they need an agent, which means they are ready to take the next step in buying or selling a property.
Costs can include estate administration expenses, title and settlement charges, negotiated agent fees, property carrying costs, and applicable taxes. Which expenses are paid by the estate or individual beneficiaries depends on the circumstances.
Inherited property's tax basis is often based on its fair market value at the date of death, or another permitted valuation date, and may be higher or lower than the deceased owner's basis. Exceptions and later adjustments can apply. A quick sale does not automatically eliminate tax.
Taxable gain or loss generally depends on the amount realized and adjusted basis, not simply how long you owned the property. Keep valuation and expense records and ask an estate attorney or tax professional to review the property's ownership, basis, and tax treatment.
Related links:
Seeking Agents® makes matching opportunities available according to your service area, active plan, account eligibility, and available buyer or seller requests. Notifications follow your plan's matching rules and applicable notification settings.
Starter matching requires at least one available, unexpired token. A token reserved for a pending offer is not available for another offer. If no usable tokens remain, upgrading to Basic or an eligible token return can restore matching under the applicable plan rules. Paid-plan matching and the ability to submit a token-funded offer are separate: submitting an offer still requires an available token.
No plan guarantees a particular number of requests, notifications, connections, or completed transactions.
Offer Tokens are used for standard offers to represent a buyer or seller on Seeking Agents®. Submitting an offer reserves a token, making it unavailable for another offer. When you become connected, that token is consumed. Eligible rejected, withdrawn, or rescinded offers return the original token. Returning a token does not extend its expiration date.
- Starter: Two one-time Offer Tokens that do not expire.
- Standard Basic for new enrollment: Five monthly Offer Tokens. Each monthly token expires 45 days after issuance.
- Purchased tokens: Agents with an eligible active paid subscription can buy additional tokens. Purchased tokens do not expire.
Existing plan allowances may differ. Tokens belong to the agent account that receives them, have no cash value, and cannot be sold, transferred, or shared between accounts. Having tokens does not replace the plan and service-area eligibility requirements for an opportunity.
Starter is free and does not require a credit card. After completing the required verification, profile, license, and service-area setup, eligible agents receive two one-time Offer Tokens that do not expire.
Your included coverage is one permanent primary ZIP plus up to four qualifying nearby ZIPs within 10 miles, measured between ZIP center points. Starter does not include additional selectable ZIPs or recurring monthly tokens.
The Starter grant is protected against repeat claims for the same license; recreating an account does not create another free grant. Matching requires an active eligible plan and usable tokens. Opportunities are not guaranteed.
Starter and purchased tokens do not expire. Monthly plan tokens expire 45 days after issuance. Unused monthly tokens can remain available into the next billing period until their own expiration date; renewal does not extend their life.
The standard token wallet uses available monthly tokens before Starter tokens, then purchased tokens. A token reserved for a pending offer is unavailable for another offer. An eligible returned token keeps its original expiration date, so an expired monthly token does not become usable again when returned.
Your confirmed permanent service area and remaining Starter tokens are preserved when you upgrade. Standard Basic for new enrollment adds five selectable ZIPs and five monthly Offer Tokens after successful payment confirmation. The monthly tokens expire 45 days after issuance.
Upgrading does not award another Starter grant or reset the permanent primary ZIP. Existing plan versions may have different allowances. If payment confirmation is pending, check the status before submitting another payment; contact support if it does not resolve.
No. Additional token purchases require an eligible active paid subscription. Starter agents must upgrade to an eligible paid plan before buying additional tokens.
Purchased tokens do not expire. Review the quantity and price shown at checkout before paying. A token balance does not independently provide paid ZIP coverage or override the eligibility requirements for an opportunity.
Start at the agent registration page and choose an available plan. Starter is free and does not require a credit card.
- Select your plan. Choose Start Free to register for Starter.
- Enter your first and last name, email, phone number, office address, and ZIP code. The city and state are filled from the ZIP code.
- Review the Agent Service Agreement and Privacy Policy. If you agree, select their checkboxes and click Submit and Verify Email.
- Open the verification email and follow its secure link to verify your address and create your password.
- Sign in and complete the required agent profile, brokerage, and license information. Carefully confirm your permanent primary service ZIP when prompted; it cannot be changed after confirmation.
- For a paid plan, complete checkout and wait for successful payment confirmation before using its paid benefits.
Matching depends on your plan, usable tokens where required, service area, and available requests. The images below show the current narrow-screen layout; the same controls may appear side by side on larger screens.
Select any image to enlarge it.
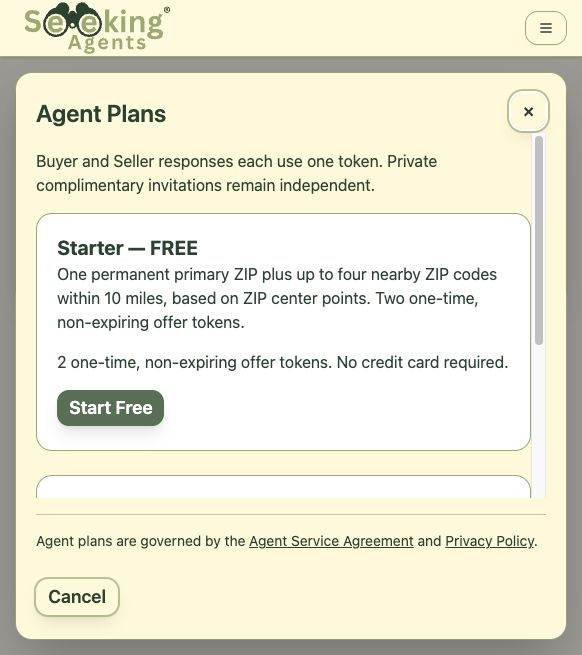
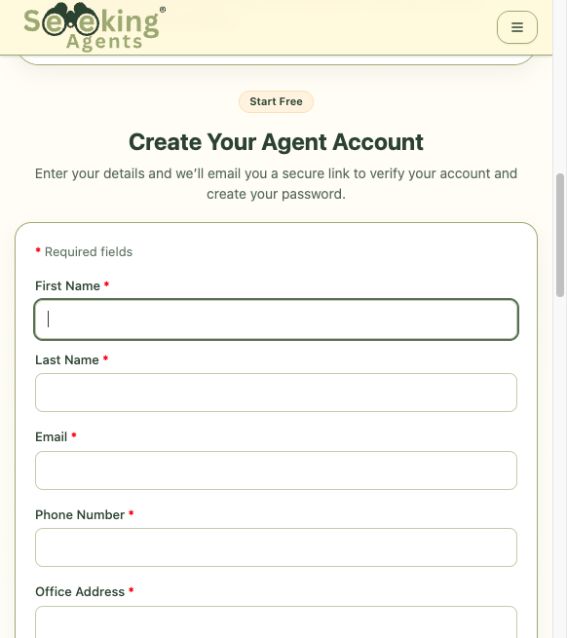
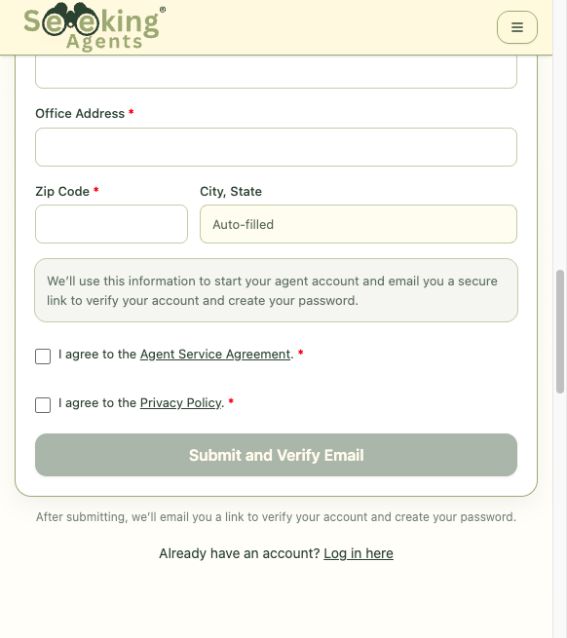
Your service area determines which locations are included in matching, subject to your plan and account eligibility.
- Included permanent coverage: One confirmed primary ZIP plus up to four qualifying nearby ZIP codes within 10 miles, measured between ZIP center points. Fewer nearby ZIPs may qualify. These included ZIPs are locked and do not consume your additional ZIP allowance.
- Starter: Includes this permanent coverage, without additional selectable ZIPs.
- Standard Basic for new enrollment: Adds five selectable ZIP codes beyond the included permanent coverage.
Existing subscribers may have different additional ZIP allowances. Select additional ZIPs through your account within its eligibility rules. Multiple agents can cover the same ZIP; coverage is not exclusive and does not guarantee requests or offers.
No, you are not required to use an agent from Seeking Agents®. Signing up simply allows you to receive and compare offers from agents. If none of the offers meet your expectations, you are free to explore other options. There is no commitment or obligation.
No. Confirm your primary ZIP carefully during setup: it is permanent. Its included nearby ZIPs are locked coverage, and changing your office or contact address does not move that service area.
Eligible paid plans allow you to edit additional selectable ZIPs within the plan allowance. Those selections are separate from permanent coverage. Contact support if you believe your account has a data error; do not assume that creating another account will reset your primary ZIP or Starter grant.
Canceling subscription renewal stops the next renewal; paid benefits continue through the end of the paid period. After that period ends, paid-only benefits, including additional matching coverage, no longer apply unless another eligible paid plan is active. An existing eligible Starter plan may provide fallback benefits.
Canceling renewal does not turn monthly tokens into non-expiring tokens: they retain their original 45-day expiration. Starter and purchased tokens retain their non-expiring status, but having a token balance does not by itself activate a plan or provide paid coverage. Check your account for the effective plan, eligible service area, and available balance.
Plans can have different enrollment versions. An existing subscription may retain allowances or terms that differ from the current offering for new agents. For example, standard Basic for new enrollment includes five monthly tokens and five additional selectable ZIPs, while some earlier contracts have different allowances.
Use the plan details in your account and your subscription terms to confirm your benefits. A change to the public plan catalog does not automatically move an existing subscriber to a new contract. Contact support before changing plans if you need help understanding how a change would affect your account.
Most buyers and sellers should compare at least two or three agents before choosing one. Look at experience, communication, pricing, proposed strategy, and how clearly each agent explains tradeoffs. Our agent interview guide and agent comparison page can help you structure the decision.
- Compare agent proposals to find the best fit.
- Ask agents questions before making a decision.
- Choose to connect with an agent when you’re ready.
If none of the offers meet your expectations, you are under no obligation to proceed.
Ask about recent experience in your area, communication style, pricing strategy, commission, services included, negotiation approach, and how the agent handles problems after an offer is accepted. Use our questions to ask a real estate agent guide to prepare before you choose.
Seller closing costs often include agent commission, title or escrow fees, transfer taxes, recording fees, mortgage payoff items, repair credits, and any concessions negotiated with the buyer. The real estate commission calculator can help estimate commission scenarios, and our commission comparison guide explains why agent fees can vary.
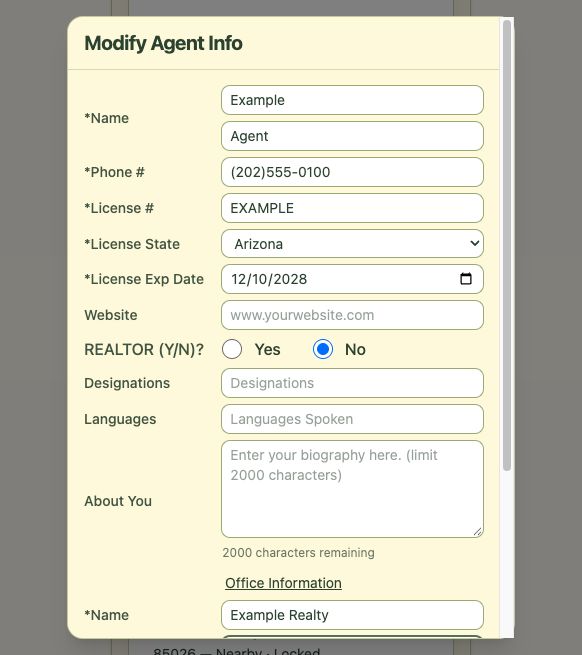
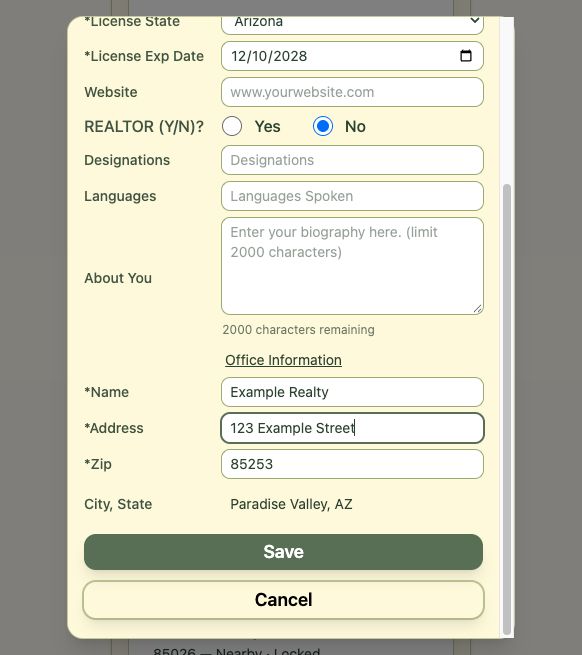
From your agent dashboard, open Profile, then select Modify Agent Info.
- Review your name and phone number.
- Enter or update your license number, license state, and expiration date. Keep this information accurate and current.
- Add optional information such as your website, REALTOR® status, designations, languages, and biography.
- Scroll to Office Information and review your office name, address, and ZIP code. Check the resulting city and state.
- Click Save to submit valid changes. Use Cancel and confirm discarding changes if you do not want to save them.
Required fields are marked with an asterisk. Contact support if you need to change the license associated with your confirmed permanent service area. Updating your office or contact address does not move your permanent primary ZIP.
The screenshots use fictional example details in an unsaved form. Enter your own valid professional information; do not copy the example license number.
Select any image to enlarge it.
Offers depend on participating agents, coverage, and interest in your request. Seeking Agents® does not guarantee that you will receive an offer or a particular number of offers.
Check that your request details and location are accurate, return to review your dashboard, and contact support if you suspect a technical problem. You remain free to explore other ways to find an agent.
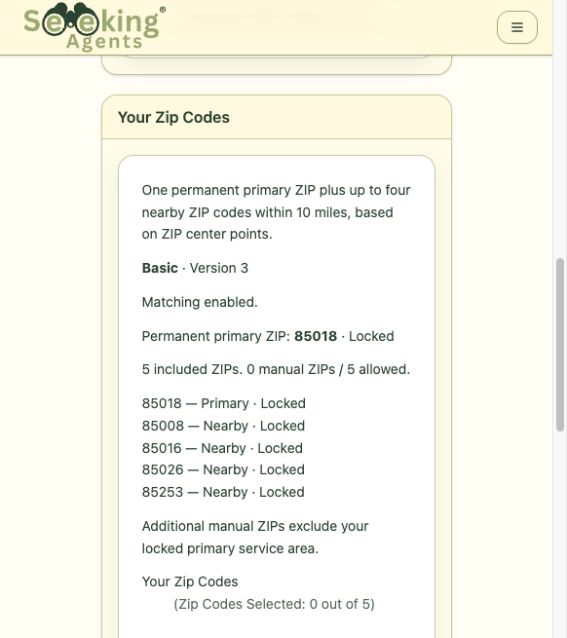
Open your agent Profile and find Your Zip Codes. Your confirmed primary ZIP and included nearby ZIPs are locked permanent coverage. They do not count against your additional manual ZIP allowance and cannot be replaced through the additional-ZIP selector.
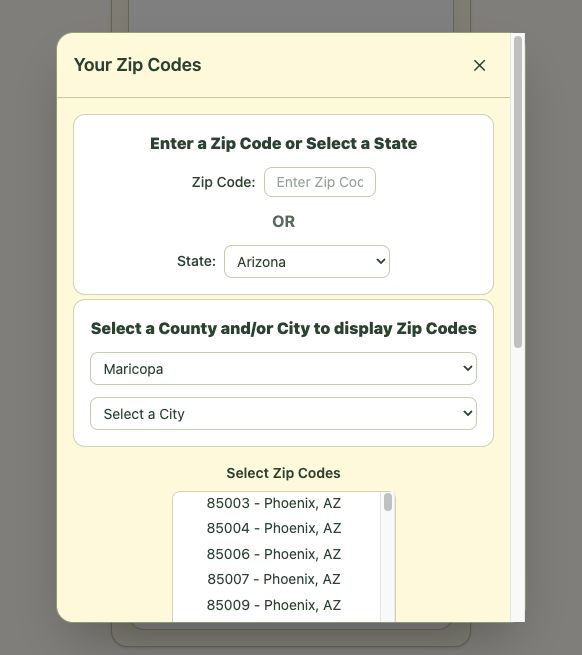
- For an eligible paid plan, open the ZIP selection dialog from the Your Zip Codes section.
- Enter a ZIP directly, or choose a state and then a county and/or city to display available ZIPs.
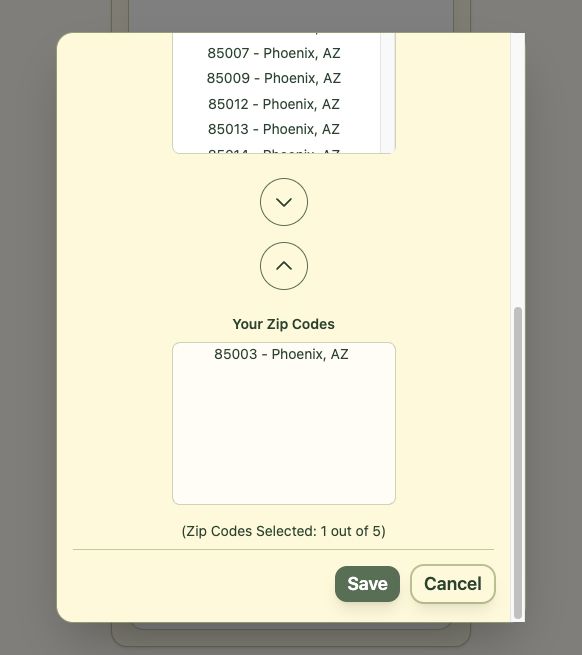
- Select the ZIPs you want and use the Add Zip arrow to move them into Your Zip Codes. Use Remove Zip to remove an additional selection.
- Check the selected count against your allowance, then click Save. On a narrow screen, scroll within the dialog to reach the selection lists and Save/Cancel controls.
- To leave without saving, click Cancel and confirm that you want to discard any pending changes.
Standard Basic for new enrollment allows five additional ZIPs. Existing allowances may differ. Starter does not include additional selectable ZIPs. The example selection below was not saved and does not change the locked service area.
Select any image to enlarge it.
Your contact information is NEVER SHARED with agents until you decide to connect with one.
This means you won’t receive unwanted calls or emails until you are ready to engage with an agent.
The first step is assessing your financial readiness:
Seeking Agents® can help guide you!Take an honest look at your financial situation to determine how much house you can afford. Review your monthly income, how much you’ve saved for a down payment, and your current debts like credit cards, car loans, or student loans. Lenders use this information to calculate your debt-to-income ratio, a key factor in loan approval. The stronger your financial foundation, the better positioned you’ll be to buy a home with confidence.
Start with a monthly housing budget that leaves room for other debts, regular expenses, emergencies, and savings. Include mortgage principal and interest, property taxes, insurance, any mortgage insurance, HOA charges, utilities, and maintenance.
Lenders assess income, debts, credit, assets, and the loan program. Debt-to-income limits vary; there is no single percentage that guarantees approval or makes a payment comfortable for your household. A pre-approval amount is a borrowing limit, not a recommended spending target.
Estimate your down payment and closing costs separately, and ask a lender for figures based on your circumstances. Any negotiated commission credit or savings must be confirmed and permitted under the transaction and loan rules before you rely on it.
Related links:
Sometimes. A buyer credit, reduced fee, or seller concession may help with cash needed at closing, but lender rules, loan type, and local program limits matter. Start with the home affordability calculator, then compare agent proposals so you understand any savings or credits before relying on them in your budget.
A down payment is the portion of the purchase price you pay from your own funds or an eligible source rather than financing through the mortgage. The required amount depends on the loan, property, and borrower.
Some eligible conventional loans allow a low down payment; FHA loans have their own down-payment and credit requirements. Eligible VA and USDA borrowers may qualify for no-down-payment financing, subject to program rules. Closing costs and reserves may still be required.
A larger down payment can reduce borrowing and may affect mortgage insurance, but compare the full loan costs and preserve adequate savings. Ask your lender to verify available programs, minimum funds, and assistance eligibility.
Private mortgage insurance (PMI) protects the lender if a borrower defaults. It is commonly required on conventional mortgages with a down payment below 20%, although the loan structure and lender requirements matter. Its cost depends on the loan and borrower; ask your lender for the actual charge.
For many covered conventional mortgages, borrowers can request cancellation when the scheduled principal balance reaches 80% of the property's original value, subject to conditions. Automatic termination generally occurs at the scheduled 78% point if the loan is current. Different rules can apply to other loan types, property types, or cancellation requests based on an updated value.
FHA mortgage insurance is different from conventional PMI. Ask your servicer which rules and requirements apply to your loan.
Closing costs are expenses paid to complete the purchase in addition to your down payment. They can include lender charges, appraisal, title and settlement services, recording or transfer charges, and prepaid taxes or insurance. Costs vary by property, location, lender, and loan.
Use your lender's Loan Estimate and Closing Disclosure, together with the settlement provider's figures, to plan the cash you need. Any buyer-agent fee you owe depends on your written agreement and negotiated contributions; it is not a fixed or universal percentage.
Seller contributions or credits must be negotiated and satisfy your loan's rules. Avoid treating an online cost range as a quote for your transaction.
Review your credit reports for errors, make payments on time, and work on reducing outstanding revolving balances. Avoid opening new credit accounts or making large financed purchases before or during a mortgage application without discussing the effect with your lender.
Credit requirements and pricing depend on the loan program, lender, and the rest of your financial profile. No single credit score guarantees approval or a particular rate. Ask a lender or HUD-approved housing counselor for guidance before taking steps intended to improve mortgage eligibility.
First-time buyers may consider conventional mortgages, FHA-insured loans, VA loans for eligible borrowers, and USDA programs for eligible borrowers and properties. State and local housing agencies may also offer down-payment or closing-cost assistance.
These options have different credit, income, property, occupancy, down-payment, insurance, and fee requirements. Some are also available to repeat buyers. Compare lender Loan Estimates and confirm current eligibility rather than choosing solely on the advertised down payment.
Related links:
Yes, programs like FHA loans, VA loans, or USDA loans help with low/no down payments. Additionally, state and local governments offer grants or forgivable loans (e.g., up to $15,000 in some areas) for down payments/closing costs. Eligibility often requires income below a regional median and homebuyer education.
Find programs in your stateThe home buying process generally takes **30 to 90 days** from pre-approval to closing, though timelines can vary based on your specific circumstances. Here's a typical breakdown:
- Pre-approval: 1–2 weeks
- House hunting: Varies depending on your availability and market conditions
- Offer to acceptance: 1–7 days
- Inspection period: 7–10 days
- Closing period: 30–45 days, depending on your lender and financing
Some of these steps can overlap—for example, your lender can begin processing your loan while you're in the inspection period. Delays can occur due to financing issues, appraisal problems, or inspection findings, so it's wise to stay flexible and responsive throughout the process.
For a full walkthrough, see the home buying process guide.
Yes, pre-approval shows sellers you’re serious and clarifies your budget. It involves a lender reviewing your finances and issuing a letter valid for 60-90 days. It’s not a final commitment but speeds up the process later. The mortgage pre-approval guide explains the steps in more detail.
To get pre-approved for a mortgage, lenders typically require the following documents:
- Proof of income: Recent pay stubs (usually the last 30 days)
- Tax returns: Last 2 years of federal tax returns and W-2s or 1099s
- Bank statements: Last 2–3 months of checking and savings account statements
- Identification: A valid government-issued ID (driver’s license or passport)
- Credit information: Your lender will pull your credit report with your consent
- Employment verification: Employer contact info and possibly a written verification
- Debt information: Details on any current debts, like student loans, car payments, or credit cards
Having these documents ready will help speed up the pre-approval process and show sellers you’re a serious, qualified buyer. The mortgage pre-approval guide explains what to expect next.
While it’s not legally required to use a real estate agent when buying or selling a home, having one can make the process much smoother, less stressful, and often more successful. A good agent can help you:
- Navigate the local market and pricing trends
- Find homes that meet your needs faster
- Negotiate offers, inspections, and repairs
- Handle contracts and paperwork correctly
- Connect you with trusted lenders, inspectors, and other pros
Use Seeking Agents® to help compare real estate agents who will work for you on your terms. Review questions to ask a real estate agent before you choose.
A great agent is your advocate and guide through one of the biggest financial decisions you’ll ever make—so it’s worth finding the right fit!
The main difference comes down to who they represent in the transaction:
- Buyer’s Agent: Works on behalf of the buyer. They help you find homes, schedule showings, write offers, negotiate terms, and guide you through inspections and closing. Their goal is to protect your interests and help you get the best deal.
- Seller’s Agent (also called a Listing Agent): Represents the seller. They help price the home, market it, manage showings, and negotiate offers to get the best possible terms for the seller.
While both agents may work on the same transaction, their duties and loyalty are to their respective clients. In some cases, one agent may represent both parties—this is called dual agency and is only legal in some states with proper disclosure and consent.
Having a dedicated agent on your side—whether you're buying or selling—helps ensure your needs and goals are prioritized throughout the process.
Use Seeking Agents® to find an agent that fits YOUR needs at YOUR price. For more context, see our buyer and listing agent guide.
Choosing the right neighborhood is just as important as choosing the right home. Here are some key things to consider when figuring out what’s right for you:
- Commute & Transportation: How long will it take to get to work or school? Is public transportation available if you need it?
- Lifestyle & Amenities: Do you want to be near restaurants, parks, nightlife, gyms, or shopping? Think about what you do most during the week.
- Schools: Even if you don’t have kids, good schools can affect property value and future resale. If you do have kids, look into ratings and reviews.
- Safety: Check local crime rates and talk to people who live in the area to get a feel for how safe it feels day and night.
- Vibe & Community: Walk or drive around the neighborhood at different times of day. Does it feel welcoming? Do you see people out walking dogs, biking, or chatting?
- Affordability: Make sure home prices and property taxes in the area fit your budget.
- Future Growth: Look into city plans, new developments, or signs of revitalization that could affect property values over time.
Working with a local real estate agent that you find on Seeking Agents® can help you narrow things down based on your lifestyle, goals, and budget. Our first-time buyer home checklist can also help you compare neighborhoods and home features. They often know the character of different neighborhoods even beyond what online research shows.
As a first-time buyer, it’s easy to get swept up in the excitement—so it helps to focus on what really matters. Here are some key things to look for:
- Location: Choose an area that fits your lifestyle, commute, and future plans. A great home in the wrong location can quickly lose its appeal.
- Budget: Stay within your pre-approval range and remember to factor in taxes, insurance, utilities, and potential repairs or upgrades.
- Condition of the home: Pay attention to the age of the roof, HVAC, plumbing, and electrical systems. Cosmetic fixes are easier than major repairs.
- Layout & space: Think about how you’ll use the space day-to-day. Does the layout work for your lifestyle? Is there room to grow?
- Resale potential: Even if you plan to stay for a while, look for features that help with resale—like good schools, curb appeal, and a functional floor plan.
- Home inspection results: Always get a professional home inspection to uncover any hidden issues before you commit.
- Your must-haves vs. nice-to-haves: Make a list before you start touring homes so you can stay focused on your priorities.
Working with a real estate agent you find on Seeking Agents® can also help you see the big picture and avoid common first-time buyer pitfalls. The first-time buyer home checklist gives you another way to stay focused. It’s a big step—but with the right guidance, it can also be a smooth one!
Deciding between a fixer-upper and a move-in-ready home depends on your budget, timeline, and comfort with renovations. Here are some factors to help you weigh your options:
- Budget: Fixer-uppers often have a lower purchase price, but renovation costs can add up quickly. Be sure to budget for repairs, permits, and unexpected expenses.
- Time & effort: A move-in-ready home saves you time and hassle, while a fixer-upper requires patience, planning, and possibly temporary housing during renovations.
- Skill level: If you're handy or have access to reliable contractors, a fixer-upper can be a rewarding investment. If not, you may want to avoid major projects.
- Customization: Fixer-uppers offer the chance to design the home to your tastes. Move-in-ready homes may require some compromises on finishes or layout.
- Financing: Some loan types (like FHA 203(k)) can help finance renovations, but they have specific requirements. Traditional mortgages are simpler for move-in-ready homes.
- Market conditions: In a hot market, fixer-uppers may be one of the few affordable options. In a slower market, you may have more room to negotiate on updated homes.
Ultimately, the right choice depends on your goals, lifestyle, and willingness to take on a project. If you're unsure, your real estate agent can help assess potential homes and estimate renovation needs. You can also review how to spot a smart home buy before taking on a fixer-upper.
Comparing home prices across different areas helps you get a sense of value and affordability. Here are some effective ways to do it:
- Use real estate websites: Sites like Zillow, Redfin, and Realtor.com let you compare listings by neighborhood, city, or ZIP code. You can filter by price, size, features, and more.
- Check price per square foot: This metric gives you a quick way to compare the value of homes in different areas, regardless of size.
- Look at recently sold homes: Recent sale prices offer a more accurate picture than listing prices alone. Most real estate platforms include this data.
- Ask real estate agents found on Seeking Agents®: A knowledgeable agent can provide hyper-local insight into price trends, neighborhood demand, and hidden gems.
- Consider long-term value: Look at factors like school ratings, nearby development, safety, and amenities that can impact home values over time.
Taking the time to compare areas side-by-side helps ensure you’re getting the most for your money—and finding a location that fits your lifestyle and goals. The home affordability calculator can help you compare price ranges against your monthly budget.
There’s no magic number when it comes to how many homes you should see—some buyers find the right fit after a few showings, while others may tour a dozen or more. The key is to feel confident in your choice. Here are some tips to help guide the process:
- Start with online research: Browsing listings online helps you get a feel for what’s available in your price range and preferred area before visiting in person.
- Focus on your priorities: Make a list of must-haves and nice-to-haves. This keeps your search focused and prevents decision fatigue.
- Quality over quantity: It’s better to view fewer homes that closely match your needs than to see dozens that aren’t a good fit.
- Take notes & compare: Keep track of what you liked and didn’t like about each property. Photos, notes, and a simple scorecard can help you remember details.
- Don’t rush—but don’t overthink: If a home checks your boxes and feels right, trust your instincts. The right one may come sooner than expected.
Work closely with your real estate agent—they can help you identify strong contenders quickly and avoid wasting time on homes that don’t meet your goals.
When a home is listed as “contingent” or “pending,” it means the seller has accepted an offer, but the sale hasn’t fully closed yet. Here’s the difference between the two:
- Contingent: The home is under contract, but the sale depends on certain conditions (or contingencies) being met—like a home inspection, financing approval, or appraisal. If any of these fall through, the deal could be canceled and the home may go back on the market.
- Pending: All major contingencies have been satisfied, and the sale is moving toward closing. It’s further along in the process than a contingent listing, but not officially sold yet.
You can still ask your agent about contingent or pending homes in case the deal falls through—but your chances of buying it are lower than with an active listing.
Online home value estimates like Zillow’s Zestimate can be a helpful starting point, but they’re just that—a starting point. They’re often off by 5–10% or more because they don’t account for things like a home’s interior condition, recent renovations, or unique neighborhood trends. For a more accurate valuation, it’s best to connect with a local real estate expert through Seeking Agents®.
Determining if a house is overpriced takes a bit of research and comparison. Here are some signs to watch for:
- Price vs. recent sales: Compare the home’s asking price to similar nearby homes (comps) that have sold recently. If it’s significantly higher without clear upgrades, it might be overpriced.
- Days on market: If the home has been sitting on the market longer than others in the area, it could be a sign the price is too high.
- No recent upgrades: A high price with an outdated kitchen, bathrooms, or major systems (roof, HVAC) might not be justified.
- Low appraisal: If you're under contract and the home appraises below the offer price, that’s a strong indicator it may be overpriced.
- Lack of interest: If there’s little buyer activity or no competing offers in a hot market, pricing may be the issue.
To get a clearer picture, compare local agents through Seeking Agents® agent comparison. They can provide a free comparative market analysis (CMA) and help you understand whether a home is fairly priced or not.
A Comparative Market Analysis (CMA) is a report prepared by a real estate agent that estimates a home’s current market value based on recently sold, similar properties in the same area. It takes into account factors like:
- Location and neighborhood
- Home size and layout
- Condition and upgrades
- Lot size and features (like pools or garages)
- Recent sale prices of comparable homes (called “comps”)
A CMA gives you a realistic price range for a home—whether you’re buying, selling, or just curious. It’s not an official appraisal, but it’s a powerful tool for understanding local market value.
Be sure to request a free CMA from agents you connect with on Seeking Agents® to make smarter, more confident decisions when entering the market.
Making an offer on a house involves a few important steps to ensure your offer is strong and competitive. Here's a simple breakdown:
- Get pre-approved for a mortgage: Having pre-approval from a lender shows the seller you're a serious buyer with the financial backing to make a purchase.
- Work with your real estate agent: The local agent you found on Seeking Agents® will help you determine a fair offer based on comparable home sales (CMA) and current market conditions.
- Consider the offer price: Look at the asking price and adjust based on factors like home condition, how long it's been on the market, and how competitive the market is. You may offer below the asking price, full price, or above in a competitive market.
- Include contingencies: These are conditions that must be met for the deal to go through (such as home inspection, financing, or appraisal). These protect you during the process.
- Submit the offer: Once you’ve decided on your offer, your agent will submit it to the seller’s agent in writing. The seller can either accept, reject, or counter your offer.
- Negotiate: If the seller counters your offer, you can negotiate on price, contingencies, or closing dates until both parties agree.
Once your offer is accepted, you’ll move on to the next steps, including a home inspection and finalizing financing.
For more offer strategy, review our offers and negotiations guide.
An earnest money deposit is a sum of money you put down when making an offer on a home to show the seller you're serious about buying. It acts like a good-faith deposit and is typically held in escrow until closing.
The amount varies depending on the local market, but it’s usually between 1% and 3% of the purchase price. For example, on a $300,000 home, you might offer $3,000 to $9,000 in earnest money.
If the sale goes through, the deposit is applied toward your down payment or closing costs. If the deal falls through due to a contingency (like financing or inspection), you usually get the deposit back. However, if you back out without a valid reason, the seller may keep it.
A local real estate agent through Seeking Agents® can help you decide on an appropriate deposit amount and make sure your money is protected throughout the transaction.
Contingencies are conditions in your offer that must be met for the sale to move forward. They protect you as the buyer and give you a legal way to back out if something goes wrong. Common contingencies to include are:
- Home inspection contingency: Allows you to have the home professionally inspected. If major issues are found, you can renegotiate or walk away.
- Financing contingency: Gives you time to secure a mortgage. If your loan isn’t approved, you can cancel the contract without losing your earnest money.
- Appraisal contingency: Protects you if the home appraises for less than your offer. You can renegotiate the price or exit the deal.
- Title contingency: Ensures the seller has a clear title to the home with no legal claims or liens that could affect your ownership.
- Sale of current home contingency (if applicable): Lets you make the purchase conditional on selling your existing home first.
The contingencies you include depend on your situation and the competitiveness of the market. A local agent through Seeking Agents® can help you structure your offer strategically and protect your interests. The offers and negotiations guide can help you understand the tradeoffs before you decide.
Once you submit an offer, a seller typically has 24 to 72 hours to respond, depending on what’s written in the offer or local market norms. However, in a fast-moving market, some sellers may respond the same day—especially if there are multiple offers.
Here are the most common types of responses:
- Acceptance: The seller agrees to your terms, and you're officially under contract.
- Counteroffer: The seller proposes changes, such as price, closing date, or contingencies. You can accept, reject, or counter again.
- Rejection: The seller declines your offer without a counter. You can submit a new offer or move on.
During this period, your agent—especially one through Seeking Agents®—can help you stay informed, respond quickly, and navigate negotiations if needed.
If your offer is rejected, don’t worry—it's a normal part of the home buying process, especially in competitive markets. Here’s what can happen next:
- No response or outright rejection: The seller may simply decline your offer without a counter. In this case, you can choose to walk away or submit a stronger offer.
- Counteroffer: The seller might come back with different terms—like a higher price, fewer contingencies, or a different closing date. You can accept, reject, or counter again.
- Continue your search: If you can’t reach an agreement, your agent can help you find other great homes and guide you through the next opportunity with even more insight.
Remember, rejected offers are not personal. With the right strategy and a knowledgeable agent from Seeking Agents®, you’ll be in a strong position to succeed on the next one.
Yes, you can negotiate both repairs and closing costs with the seller—especially after the home inspection. It’s a normal part of the buying process, and many sellers are open to making concessions to keep the deal moving forward.
Here are a few common negotiation options:
- Request repairs: You can ask the seller to fix specific issues before closing, especially if they involve safety, structural problems, or major systems (like the roof, HVAC, or plumbing).
- Ask for a repair credit: Instead of making the repairs, the seller may offer a credit at closing so you can handle the work yourself after moving in.
- Negotiate closing costs: You can ask the seller to contribute toward your closing costs, which helps reduce your out-of-pocket expenses. This is especially common in balanced or buyer-friendly markets.
Your real estate agent—like one from Seeking Agents®—can guide you through negotiations and help structure your requests in a way that keeps the deal on track while protecting your interests. Our inspections, appraisals, and escrow guide explains what often happens next.
A counteroffer happens when a seller doesn’t accept your original offer but wants to keep the negotiation going. They may change the price, closing date, contingencies, or other terms.
Here’s how you can respond to a counteroffer:
- Accept it: If you're happy with the new terms, you can agree and move forward with the contract.
- Reject it: If the changes don’t work for you, you can decline the counter and walk away.
- Counter again: You can propose your own changes in response. This back-and-forth can continue until both sides reach an agreement—or decide to part ways.
Time is important—most counteroffers come with a deadline. A skilled agent found on Seeking Agents® can help you evaluate your options, craft a strategic response, and negotiate confidently.
You’re likely in a bidding war when multiple buyers are making offers on the same property—usually driving the price above asking. Here are some signs that you may be in one:
- The home is newly listed and already has multiple offers: If your agent hears that several offers came in within a day or two, it’s a strong sign of a bidding war.
- The seller sets a deadline for offers: This often means they’re expecting multiple bids and want to choose the best one quickly.
- Your agent is asked for your “highest and best” offer: This is a clear indication that the seller is weighing multiple competitive offers.
- The price is escalating quickly: If the home is already above asking price and still receiving interest, you’re likely in a competitive situation.
If you’re in a bidding war, your real estate agent can help you craft a smart, strategic offer that stands out—without overpaying. You can also review our hot market offer strategies before deciding how far to stretch.
An escalation clause is a tool you can include in your offer that automatically increases your bid if a higher competing offer comes in. It tells the seller, “I’ll pay X, but if someone else offers more, I’m willing to go up to Y.”
For example, you might offer $400,000 with an escalation clause that increases your offer by $2,000 over any competing bid, up to a maximum of $420,000.
Benefits:
- Keeps your offer competitive without overpaying right away
- Saves time by avoiding back-and-forth negotiations
Risks:
- Sellers may prefer clean, straightforward offers without escalation language
- You could still end up paying more than expected
Using an escalation clause can be a smart strategy in a bidding war, but it’s not always the best fit for every situation. A local expert found on Seeking Agents® can help you decide if it makes sense based on the market and the home you're targeting; our offers and negotiation strategies guide can also help you compare options.
Once your offer is accepted, you’re officially under contract—but there are still several important steps before you reach the closing table:
- Earnest money deposit: You'll submit your good-faith deposit, which is held in escrow until closing.
- Home inspection: You'll schedule an inspection to check the condition of the home. If issues arise, you may negotiate repairs or credits.
- Appraisal: If you're financing the purchase, your lender will order an appraisal to ensure the home is worth the loan amount.
- Loan approval: You'll complete the mortgage process by submitting any final documents to your lender for underwriting and approval.
- Title search & insurance: A title company will ensure the property has no legal claims and help facilitate closing. Title insurance is also purchased at this stage.
- Final walkthrough: Typically done 24–48 hours before closing to make sure the home is in the agreed-upon condition.
- Closing: You’ll sign all paperwork, pay any remaining costs, and officially become the homeowner!
An experienced agent found on Seeking Agents® will guide you through each of these steps and help avoid any surprises along the way. The inspections, appraisals, and escrow guide gives more detail on the middle of the transaction.
Yes, getting a home inspection is highly recommended—even if the home looks perfect. A professional inspection helps uncover hidden issues like structural problems, plumbing or electrical concerns, roof damage, or mold that could cost you later.
Here’s how to arrange a home inspection:
- Schedule it promptly: Once your offer is accepted, inspections usually need to happen within 7–10 days, depending on the contract terms.
- Hire a licensed inspector: Your real estate agent found on Seeking Agents® should be able recommend trusted local inspectors.
- Attend the inspection: You’re encouraged to be there so you can ask questions and get a firsthand look at any potential issues.
- Review the report: You’ll receive a detailed report of the findings, which you can use to negotiate repairs, request credits, or in serious cases, back out of the deal (if your contract includes an inspection contingency).
Even for newer homes, a home inspection gives you peace of mind—and can save you thousands down the road. Review what to expect during a home inspection before inspection day.
If the home inspection reveals major issues—like foundation damage, a failing roof, electrical hazards, or plumbing problems—you have options. Here’s what you can do:
- Request repairs: You can ask the seller to fix the problems before closing. This is common if the issues are safety-related or impact livability.
- Ask for a credit or price reduction: Instead of making repairs, the seller might agree to lower the sale price or offer a credit at closing so you can handle the work yourself.
- Renegotiate terms: You can reopen negotiations based on the findings, especially if the cost to fix the issues is significant.
- Walk away: If the problems are too serious or the seller won’t cooperate—and you have an inspection contingency—you can back out of the deal without losing your earnest money.
A skilled agent found on Seeking Agents® can help you evaluate the report, get repair estimates if needed, and guide you through the next steps with confidence.
A title search is a review of public records to verify the legal ownership of a property and uncover any issues that could affect your right to own it. It’s usually conducted by a title company or real estate attorney during the closing process.
Here’s what a title search looks for:
- Outstanding liens: Unpaid debts (like taxes or contractor bills) that could be tied to the property
- Ownership history: Confirms the seller has the legal right to sell the home
- Easements or restrictions: Legal limitations or shared access that may affect your use of the property
- Judgments or legal claims: Any lawsuits or court rulings involving the property
The title search is essential for protecting your investment. If issues are found, they must be resolved before closing. You’ll also typically purchase title insurance, which helps protect you against future claims that weren’t found during the search.
Your real estate agent can help coordinate with a trusted title company to ensure everything is clear before you close.
Yes, you’ll need to purchase a homeowner’s insurance policy before closing—especially if you’re financing the home with a mortgage. Lenders require proof of insurance to protect the property (their collateral) in case of damage or loss.
Here’s what to know:
- Timing: Your policy must be active by the closing date. Most lenders require proof of coverage a few days before closing.
- Coverage: A standard policy typically covers damage from fire, storms, theft, and certain types of water damage, as well as liability protection.
- Payment: Your first year’s premium is often paid upfront at closing and may be included in your escrow account for future payments.
Your closing agent (either the title company or real estate attorney) will inform you of this requirement and guide you on when and how to provide proof of coverage. Your real estate agent—especially one found on Seeking Agents®—can also help you connect with trusted insurance providers.
An appraisal is a professional, third-party assessment of a home’s market value, usually ordered by your mortgage lender during the closing process. The appraiser evaluates the home based on recent comparable sales, condition, location, and features to ensure the property is worth the amount being financed.
If the home appraises for less than your offer:
- Renegotiate the price: You can ask the seller to lower the price to match the appraised value.
- Cover the difference: If the seller won’t reduce the price, you may choose to pay the difference out of pocket.
- Cancel the contract: If you included an appraisal contingency, you can walk away without losing your earnest money.
If the home appraises for more than your offer:
- Great news: You’re buying the home for less than it’s worth—instant equity!
- No changes needed: Your loan amount stays the same, and there’s no impact on your closing process.
Your lender, closing agent, and the real estate agent you found on Seeking Agents® will guide you through how to respond to the appraisal results and protect your investment. For more context, read the inspections, appraisals, and escrow guide.
Yes, in many cases you can back out of a home purchase—especially if your offer includes standard contingencies. These clauses are designed to protect you if unexpected issues come up before closing.
Here are common situations where you may be able to cancel the deal without penalty:
- Inspection issues: If the home inspection reveals major problems and you have an inspection contingency, you can walk away or renegotiate.
- Low appraisal: If the home appraises for less than your offer and you can’t reach a new agreement with the seller, an appraisal contingency allows you to exit the deal.
- Financing falls through: If your mortgage isn’t approved in time and you included a financing contingency, you won’t be forced to proceed.
- Title problems: If legal or ownership issues show up in the title search, you may be able to cancel until the issues are resolved.
If you back out for a reason not covered by your contract, you may risk losing your earnest money. That’s why it’s important to have a knowledgeable agent—like one found on Seeking Agents®—to help you structure your offer with the right protections in place.
Final mortgage approval—also known as “clear to close”—typically takes anywhere from 2 to 4 weeks after you go under contract. However, the full mortgage process from pre-approval to closing can take about 30 to 45 days in total.
Here’s what happens during the final approval stage:
- Underwriting review: After you submit all required documents (like tax returns, bank statements, and pay stubs), your lender’s underwriting team reviews everything to ensure you meet loan requirements.
- Appraisal and title check: Your lender confirms the home’s value and checks for any legal issues with the title.
- Conditions clearance: If the underwriter needs more information (called “conditions”), you’ll need to respond quickly to avoid delays.
- Final approval: Once all conditions are met, you’ll receive a “clear to close,” and your lender will schedule your closing date.
For the bigger picture, review our mortgage process guide.
An escrow account is a special account used to hold money safely during a real estate transaction or throughout your mortgage. It helps ensure that important payments—like property taxes and homeowners insurance—are made on time.
There are two types of escrow you might encounter:
- During the home purchase: Your earnest money deposit is held in an escrow account by a neutral third party (like a title company or attorney) until closing. This protects both the buyer and seller during the transaction.
- After you buy the home: If you have a mortgage, your lender may set up an escrow account to collect a portion of your annual property taxes and insurance premiums each month as part of your mortgage payment. The lender then pays those bills on your behalf when they’re due.
Escrow accounts provide peace of mind that major payments won’t be missed. Your closing agent and lender can explain exactly how your escrow will be set up and managed, and our inspections, appraisals, and escrow guide explains how escrow fits into the transaction.
The underwriting process is when your lender reviews all your financial information to determine if you qualify for the mortgage you’ve applied for. It typically happens after you’ve found a home and gone under contract—and can take anywhere from a few days to a few weeks.
Here’s what to expect:
- Document review: The underwriter will examine your income, assets, credit history, employment, debts, and any other required paperwork to ensure you meet the loan criteria.
- Property appraisal: They’ll review the home appraisal to confirm the property is worth the loan amount.
- Title and insurance verification: The underwriter ensures the title is clear and that you’ve secured homeowner’s insurance.
- Conditions may be requested: The underwriter might ask for additional documents (called “conditions”) before giving final approval. These could include updated pay stubs, bank statements, or letters of explanation.
- Clear to close: Once all conditions are satisfied, you’ll receive final approval and can move forward with closing.
Staying responsive and organized will help keep things moving smoothly. A skilled agent found on Seeking Agents® can help coordinate communication between you and your lender during underwriting.
“Closing” and “settlement” are often used interchangeably in real estate—and in most cases, they refer to the same event: the final step in the home buying process where ownership officially transfers from the seller to the buyer.
Here’s what typically happens during closing/settlement:
- Signing documents: You’ll review and sign all the necessary paperwork, including the loan documents and final disclosures.
- Paying closing costs: You’ll pay any remaining down payment and closing fees, usually via wire transfer or certified check.
- Transferring ownership: Once everything is signed and funds are distributed, the title is recorded in your name, and you receive the keys.
The terminology may vary depending on your region—some areas use “closing,” while others say “settlement.” Our closing day guide explains what comes next.
When it’s time for closing, you’ll need to bring a few important documents and items to complete the transaction. Here’s what to have ready:
- Government-issued photo ID: A driver’s license or passport to verify your identity.
- Closing disclosure: You’ll receive this at least 3 days before closing. Bring a copy for reference and to confirm all the terms.
- Certified or cashier’s check (if required): This covers your down payment and closing costs. Your closing agent will tell you the exact amount and whether a wire transfer is preferred.
- Proof of homeowner’s insurance: Lenders require an active policy before closing. Bring the declarations page or confirmation of coverage.
- Final loan documents: If your lender has sent any final documents ahead of time, bring signed copies if needed.
Your closing agent—either a title company or real estate attorney—will provide you with a full list of what’s needed for your specific transaction.
At closing, several parties may be involved—but buyers and sellers often sign their documents separately. In many cases, you and the seller won’t even be at the table at the same time.
Here’s who typically attends and what they do:
- You (the buyer): You’ll review and sign the mortgage documents, loan disclosures, and final paperwork to take ownership of the home.
- Closing agent (title company or attorney): This neutral third party manages the transaction, prepares the paperwork, collects funds, and records the new deed.
- Your real estate agent: They may attend to support you, answer questions, and help resolve any last-minute issues.
- Lender representative (sometimes): Not always present, but they may attend or be available to confirm loan details or disburse funds.
- Seller and their agent: The seller signs their portion of the documents—often before or after your signing appointment.
You will usually sign your closing documents first, often in a private appointment. The seller may sign at a different time or location, depending on the title company or attorney’s process.
Your agent, found on Seeking Agents®, and your closing agent will walk you through every step and make sure all documents are in order so you can confidently close on your new home.
While most closings go smoothly, there are a few things that can go wrong—especially if key steps were missed along the way. That’s why it’s important to stay organized and work with experienced professionals.
Here are some common issues that can delay or derail a closing:
- Last-minute loan issues: Changes in your credit, income, or employment can impact your loan approval—even at the last minute.
- Missing documents or funds: Forgetting to bring required documents or not wiring your closing funds on time can delay the process.
- Title problems: Unresolved liens, disputes over ownership, or paperwork errors can hold up the transfer of title.
- Unmet contingencies: If inspection repairs, appraisal conditions, or other contingencies haven’t been satisfied, closing may be postponed.
- Walkthrough surprises: If the home is damaged or items are missing during your final walkthrough, you may need to renegotiate before closing.
The good news? Most of these issues can be avoided with careful planning and proactive communication. Your real estate agent should work closely with your lender, title company, and the seller’s team to ensure everything is ready for a smooth closing day.
The final walk-through is your last chance to inspect the home before closing. It typically takes place within 24 to 48 hours before settlement and ensures the property is in the condition you agreed to purchase.
Here’s why it’s important:
- Confirm repairs: If the seller agreed to make repairs after the inspection, the walk-through lets you verify that the work was completed properly.
- Check for damage: You’ll make sure the home hasn’t been damaged or altered since your last visit.
- Ensure agreed-upon items are present: Appliances, fixtures, or other items that were supposed to stay with the home should still be there.
- Test systems: You can quickly test lights, plumbing, HVAC, and doors to make sure everything is functioning as expected.
The walk-through is not the time for a full inspection, but it’s a crucial step to protect your investment. If something is wrong, your agent can help you address the issue before closing.
You’ll typically receive the keys to your new home on closing day—but only after all documents have been signed, funds have been transferred, and the deed has been officially recorded with the county (which can take a few hours).
Here’s how it usually works:
- Same-day key handoff: In many cases, you’ll get the keys right after closing is completed and everything is finalized.
- Delayed recording (in some areas): In some states or counties, keys aren’t released until the deed is officially recorded, which may happen later that day or the next business day.
- Post-closing occupancy (if agreed): If the seller negotiated to stay in the home temporarily after closing (a rent-back agreement), you’ll receive the keys on the agreed-upon move-in date.
The real estate agent you found on Seeking Agents® will coordinate the key exchange and keep you updated so you know exactly when you can move in.
Closing day is a major milestone—but there are still a few things to take care of once you officially become a homeowner. Here’s what typically happens after closing:
- Receive your keys: Once the transaction is recorded and finalized, you’ll get the keys and can move into your new home.
- Set up utilities and services: Make sure electricity, water, gas, internet, trash, and other services are in your name and scheduled to start right away.
- Transfer your homeowner’s insurance: Your policy should already be in place, but it’s a good idea to confirm coverage and keep copies of your documents.
- Expect some mail: You’ll receive your official deed, mortgage documents, and other paperwork from your lender and title company in the days or weeks after closing.
- Make your first mortgage payment: Your first payment is usually due about a month after closing. Your lender will send instructions or set up an online account for you.
- Secure your home: Consider changing the locks, setting up a security system, and updating your address with the post office and other important services.
While the legal and financial part may be done, the move-in process is just beginning. Your agent, found on Seeking Agents®, can still be a valuable resource for local service providers, contractors, and advice as you settle into your new home.
If you discover problems with your new home after closing—like unexpected damage, items missing, or repairs that weren’t completed properly—it can be frustrating, but there are steps you can take to resolve the situation:
- Review your closing documents: Check your purchase agreement, inspection reports, and any repair addendums to confirm what was agreed upon in writing.
- Contact your real estate agent: A trusted agent—especially one found on Seeking Agents®—can help you understand your rights and contact the seller’s agent to try to resolve the issue quickly.
- Reach out to the closing agent or attorney: They can review what was legally documented and clarify whether the issue was addressed at closing.
- Use your home warranty (if applicable): If you received a home warranty, it may cover certain repairs or systems that fail shortly after closing.
- Seek legal advice if needed: If the issue is serious and not resolved through communication, a real estate attorney can advise you on your legal options, including potential claims for breach of contract or misrepresentation.
Most post-closing issues can be resolved through communication and documentation. Having a strong agent on your side helps you navigate any surprises with confidence.
Pre-qualification and pre-approval are both steps in the mortgage process, but they’re not the same—and understanding the difference can help you shop smarter and stand out to sellers.
- Pre-qualification: This is a quick, informal estimate of how much you might be able to borrow based on self-reported financial info (like your income and debts). It’s useful for getting a general idea of your price range, but it doesn’t carry much weight with sellers.
- Pre-approval: This is a more in-depth process where a lender reviews your actual financial documents—like pay stubs, bank statements, and credit history—to verify your ability to get a loan. You’ll receive a pre-approval letter that shows sellers you’re a serious, qualified buyer.
Bottom line: Pre-qualification is a starting point; pre-approval is a green light to shop with confidence. The mortgage pre-approval guide walks through the next steps.
When choosing a mortgage, one of the biggest decisions you’ll make is whether to go with a fixed-rate or adjustable-rate mortgage (ARM). Here’s how they differ:
- Fixed-rate mortgage: Your interest rate stays the same for the entire life of the loan (typically 15, 20, or 30 years). This means your monthly principal and interest payments remain stable, making it easier to budget long-term.
- Adjustable-rate mortgage (ARM): Your interest rate starts lower than a fixed-rate loan but can change after an initial fixed period (like 5, 7, or 10 years). After that, the rate adjusts periodically based on market conditions—meaning your payment can go up or down.
Fixed-rate loans are great if you plan to stay in the home long-term and want predictable payments. ARMs can be a smart choice if you expect to move or refinance before the rate adjusts, or if you want a lower initial payment. Compare more terms in our first-time buyer loan options guide.
Interest rates play a big role in how much your home will ultimately cost—both monthly and over the life of your loan. Even small changes in rates can significantly affect your buying power and long-term affordability.
Here’s how interest rates impact your purchase:
- Monthly payment: Higher interest rates increase your monthly mortgage payment, while lower rates reduce it—making the same home more or less affordable.
- Loan approval amount: Lenders consider your monthly payment when deciding how much to approve. If rates rise, you may qualify for a smaller loan.
- Total interest paid: Over a 30-year mortgage, a higher rate can cost tens of thousands more in interest.
- Market activity: When rates are low, more buyers enter the market—often leading to more competition. Higher rates can slow demand, sometimes leading to better deals.
Staying informed about current rates—and how they affect your budget—helps you make smarter, more confident decisions. Use the home affordability calculator to test payment scenarios, and read what drives mortgage rates for broader context.
A real estate attorney advises on legal rights and obligations, reviews documents, and can help resolve title, ownership, or contract issues. Whether an attorney must be involved in a transaction depends on state law and the work being performed; attorney involvement is not universally required. New Jersey, for example, does not generally require a homebuyer to retain an attorney.
Even where optional, independent legal advice can be useful for an inherited property, divorce, disputed title, unusual contract terms, or other complex circumstances. An attorney working for a lender or another party does not automatically represent you. Confirm whom the attorney represents and what services are included.
Yes, you can absolutely buy a home if you’re self-employed—but the mortgage process might involve a few extra steps. Lenders just need to verify that your income is stable, reliable, and sufficient to cover the loan.
Here’s what you’ll typically need to provide:
- 2 years of personal and business tax returns: Lenders will review your net income (after business expenses), not just gross revenue.
- Profit and loss (P&L) statements: Especially if your income has fluctuated, lenders may want to see year-to-date financials.
- Bank statements: To show consistent deposits and cash flow.
- Business verification: This could include a business license, a letter from your accountant, or proof of active status.
Tips to strengthen your application:
- Keep personal and business finances separate
- Maintain good credit and a manageable debt-to-income ratio
- Consider making a larger down payment to increase lender confidence
Ask a real estate agent you connected with on Seeking Agents® if they can help you connect with lenders who understand self-employment and know how to present your financial picture in the best light. Our credit and pre-approval tips can also help you prepare.
Possible federal tax benefits of homeownership include deductions for qualifying mortgage interest and certain state and local taxes when you itemize, and an exclusion of some gain on an eligible principal-residence sale. Qualification, limits, income restrictions, filing status, and the applicable tax year matter.
Do not assume a fixed state-and-local-tax deduction cap applies every year. Mortgage-insurance deductions and home-office deductions also have specific eligibility rules; working from home alone does not establish eligibility.
Review the IRS guidance for the year you are filing and consult a tax professional before estimating savings. Start with IRS guidance on deductible taxes and IRS Publication 523 on selling your home.
No results. Try another search term.
For informational purposes only. We are not a brokerage and do not provide legal advice.
Looking for more help? Explore our real estate guides or read home buying & selling articles.